

- Markets anticipate the US CPI inflation report to determine the future Federal Reserve rate path.
- Japan reported a steep -6.8% YoY drop in September household spending and a shrinking current account surplus.
- China posted a lower-than-expected trade surplus of 105.3 billion USD as commodity prices and import demand shifted.
- Geopolitical tensions in the Middle East and the Black Sea maintain a strong risk premium for crude oil markets.
- The US Dollar Index consolidates near 101.5 pts ahead of inflation data and Treasury yield movements.

- Markets anticipate the US CPI inflation report to determine the future Federal Reserve rate path.
- Japan reported a steep -6.8% YoY drop in September household spending and a shrinking current account surplus.
- China posted a lower-than-expected trade surplus of 105.3 billion USD as commodity prices and import demand shifted.
- Geopolitical tensions in the Middle East and the Black Sea maintain a strong risk premium for crude oil markets.
- The US Dollar Index consolidates near 101.5 pts ahead of inflation data and Treasury yield movements.
The session is dominated by anticipation of the key US CPI inflation report, which will determine the Federal Reserve's future rate path. Although a December rate hike seems certain, in the absence of stronger inflationary pressure, subsequent hikes may no longer be needed.
Market sentiment remains cautious due to rising geopolitical risks in the Middle East (intercepted missile and drone attacks on Saudi Arabia and the evacuation of American aircraft from British bases) and in the Black Sea. On the other hand, yesterday's rebound on Wall Street and sharp drops in oil prices show that the market may be transitioning from a period of panic to euphoria.
A series of mixed data releases has already arrived from Asia: Japanese household spending slumped by -6.8% YoY compared to the forecast of -3.1% YoY, Japan's current account balance came in significantly below expectations (JPY 1.82 trillion vs JPY 2.81 trillion), and consumer as well as business sentiment in Australia remains deep in defensive territory. China reported a trade surplus below consensus (USD 105.3 billion vs USD 126.5 billion), although export growth itself maintained a solid pace. The afternoon will be dominated by the US consumer price index (CPI) reading at 14:30 and numerous speeches from FOMC and BoE members.
Key Releases from the Asian Session
- China: The trade balance surplus in dollar terms fell in October to USD 105.3 billion (consensus: USD 126.5 billion; previous: USD 133.5 billion), and in yuan terms to CNY 713 billion (forecast: CNY 855 billion). Despite dynamic exports, the overall trade balance clearly slowed down under the influence of commodity prices and import demand changes.
- Japan: Household spending plummeted in September by as much as -6.8% YoY against a forecasted decline of -3.1% YoY (previous: -3.1% YoY), confirming the still fragile condition of the Japanese consumer. The current account surplus shrank to JPY 1.82 trillion (JPY 2.81 trillion expected).
- Japan: The Economy Watchers sentiment index fell to 46.1 pts (consensus: 47.1 pts; previous: 47.0 pts). Bank lending grew by 5.2% YoY (below the forecasted 5.4% YoY).
- Australia: Westpac Consumer Sentiment improved slightly to -2.7% MoM (previous: -4.7% MoM), but NAB Business Confidence worsened further, dropping to -15 pts (previous: -14 pts).
- United Kingdom: BRC Retail Sales Monitor rose by 1.1% YoY, coming in slightly below market consensus at 1.2% YoY (previous: 1.0% YoY).
Macroeconomic Calendar (CET)
- 09:30 UK - Speech by MPC member (Sarah Breeden)
- 10:00 US - Speech by FOMC Board member (Christopher Waller)
- 12:00 US - NFIB Small Business Optimism Index. Consensus: 98.0 pts. Previous reading: 97.9 pts.
- 13:30 UK - Speech by BoE Deputy Governor (Clare Lombardelli)
- 14:15 US - ADP Weekly Employment Change
- 14:30 US - Core CPI MoM. Consensus: 0.2%. Previous reading: 0.3%.
- 14:30 US - Consumer Price Index (CPI) MoM. Consensus: 0.3%. Previous reading: 0.6%.
- 16:50 US - Speech by Dallas Fed President (Lorie Logan)
- 19:01 US - 10-Year Treasury Note Auction. Previous reading: yield 5.30%, bid-to-cover 2.8.
- 19:30 Canada - Bank of Canada (BOC) Summary of Deliberations
- 19:30 UK - Speech by BoE Chief Economist (Huw Pill)
- 19:30 US - Speech by Kansas City Fed President (Jeffrey Schmid)
- 21:30 US - Speech by FOMC Board member (Michelle Bowman)
- 22:30 US - API Weekly Crude Oil Stock Report
- During the day: China - M2 Money Supply YoY. Consensus: 7.2%. Previous reading: 7.2%.
- During the day: China - New Yuan Loans. Consensus: CNY 80 billion. Previous reading: CNY 1080 billion.
- All day Global - G7 Meetings (Day 2)
Corporate Earnings
- Petroleo Brasileiro S.A. - Petrobras (PBR) — after market, EPS forecast: USD 1.38; key barometer of profitability in the global emerging markets oil sector and dividend policy.
- Vodafone Group Plc (VOD) — before market, no official EPS forecast; indicator of European telecommunications sector health and asset restructuring progress.
- Ecopetrol S.A. (EC) — after market, EPS forecast: USD 0.62; representative of the Latin American extraction sector amid growing oil price uncertainty.
- Venture Global, Inc. (VG) — before market, EPS forecast: USD 0.50; key entity in the US liquefied natural gas (LNG) export segment to Europe and Asia.
- CoreWeave, Inc. (CRWV) — after market, EPS forecast: USD -1.45; key representative of cloud infrastructure dedicated to artificial intelligence (AI).
- On Holding AG (ONON) — before market, EPS forecast: USD 0.42; gauge of luxury goods and sports segment consumer resilience to global inflationary pressure.
- Telefonica Brasil S.A. (VIV) — after market, EPS forecast: USD 0.24; barometer of telecom demand in Latin America's largest market.
- Embraer S.A. (EMBJ) — before market, EPS forecast: USD 0.87; insight into order backlog and regional aircraft demand.
Markets to Watch
- Crude Oil (WTI / Brent) — Military tensions in the Middle East (drone attacks in Saudi Arabia) and a strike on a tanker in the Black Sea create a strong geopolitical risk premium, while the evening API inventory report in the US will provide direction regarding physical demand.
- USD (US Dollar / DXY) — The core and headline CPI releases at 14:30 will be the main catalyst of the session; a lower reading will solidify expectations for Fed rate cuts, weakening the dollar, while an upside surprisewill trigger a dynamic rally in the US currency.
- US 10-Year Treasury Yields (US10Y) — Will react directly to the CPI inflation report and the evening 10-year Treasury note auction (19:01), setting the tone for overall global equity market sentiment.
Technical Outlook on the US Dollar Index
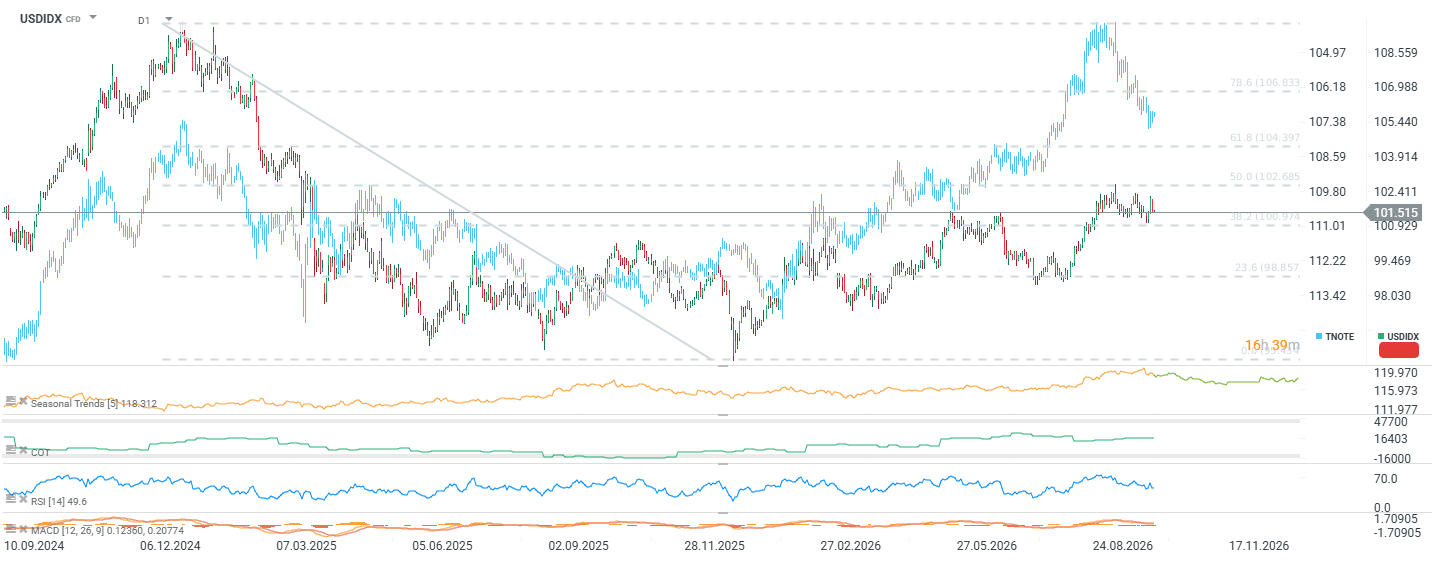
The Dollar Index is trading near 101.5 pts and has been consolidating for several weeks between the 38.2% (100.97 pts) and 50.0% (102.69 pts) retracements of the decline from late 2024 and early 2025. The bounce from the November 2025 low (around 95.5 pts) stalled just below the 50.0% retracement, where sellers have clearly defended since September. RSI(14) at 49.6 is neutral, and the MACD lines are flattening near zero, indicating momentum has faded and neither side holds an advantage. The dollar has tracked US Treasury yields closely (TNOTE inverted), so their recent pullback from year-to-date highs explains why the breakout stalled. However, a bullish scenario is supported by COT positioning, which remains net-long and rising, along with seasonality that tends to favor the USD through year-end. Key support lies at 100.97 pts: a break below would open the door toward the 23.6% retracement (98.86 pts). Conversely, a breakout above 102.69 pts would shift attention to the 61.8% retracement at 104.40 pts.


BREAKING: US CPI data higher than expected 🚩 Wall Street reacts


⬇️EURUSD pulls back ahead of CPI


Market Wrap: European Stocks Rise, Infineon Shares Up 5% 🔼 Wall Street Weakens Ahead of U.S. CPI

Waller’s hawkish Fed remarks drive USDIDX rebound 🗽 Is a 50 bp U.S. rate hike possible?
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.